What Is a Title Commitment? A Guide for Land Buyers and Sellers

What Is a Title Commitment for Land Buyers?

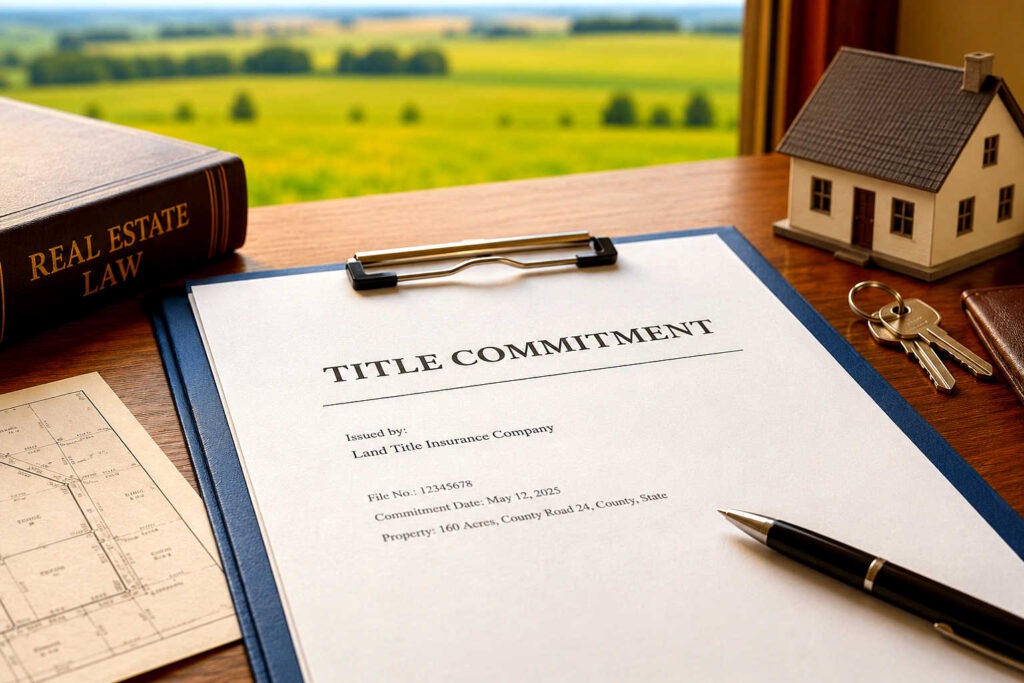
A title commitment is a document issued by a title insurance company that explains the conditions under which it is prepared to provide title insurance for a property. It identifies key information about the property and proposed transaction, lists requirements that may need to be completed before closing, and outlines exceptions that may not be covered by the final title insurance policy.

For buyers and sellers of farm land, ranch land, recreational property, and other rural acreage, reviewing the title commitment can be an important part of the closing process. Easements, liens, rights-of-way, ownership issues, legal descriptions, and other recorded matters can affect how a property is transferred or used.

Understanding what a title commitment contains can help you recognize potential issues early and know which questions to ask before the transaction moves forward.

What Is a Title Commitment in Real Estate?

A title commitment is a document prepared by a title insurance company before closing that outlines the conditions under which it is willing to issue a title insurance policy. It provides important information about the property, identifies the parties involved in the proposed transaction, and lists requirements and exceptions that may affect the final policy.

In a real estate transaction, the title commitment helps buyers, sellers, lenders, and other parties understand whether there are recorded matters that need attention before ownership changes hands. These may include liens, easements, rights-of-way, ownership discrepancies, restrictions, or other issues found during the title search.

For buyers of farm land and other rural property, the title commitment can be especially important because access, legal descriptions, easements, mineral reservations, and other recorded interests may have a direct impact on how the land can be used.

A title commitment is not the same thing as the final title insurance policy. Instead, it is a commitment for title insurance that explains what must happen before the insurer will issue coverage and which matters may be excluded from that coverage.

How Does the Title Commitment Process Work?

A title commitment is typically prepared after the title company reviews public records and other documents related to the property. This review helps identify ownership information, liens, easements, restrictions, and other recorded matters that could affect the transaction.

Once the title search is complete, the title company issues the commitment outlining the conditions that must be satisfied before a title insurance policy can be issued. The buyer, seller, lender, and other parties involved in the transaction may then review the document and address any outstanding requirements or concerns before closing.

The title commitment process generally includes:

  1. Title search – The title company researches public records to review the property’s ownership history and identify recorded claims, liens, easements, or other matters affecting title.
  2. Commitment preparation – Based on the search, the title company prepares the title commitment and lists the requirements that must be completed before coverage can be issued.
  3. Review of requirements and exceptions – Buyers, sellers, lenders, and their advisors can review the commitment to determine whether any listed items need to be resolved or investigated further.
  4. Resolution of title issues – Outstanding mortgages, liens, documentation problems, or other requirements may need to be addressed before closing can proceed.
  5. Closing and issuance of the title policy – After the required conditions are satisfied and the transaction closes, the title insurer can issue the final title insurance policy subject to its terms, conditions, and exceptions.

For rural land transactions, this review may also uncover matters such as access easements, rights-of-way, mineral reservations, or legal-description issues that deserve careful attention before the property changes ownership.

What Is Included in a Title Commitment?

A title commitment is usually organized into sections that explain the proposed insurance coverage, the property being insured, the requirements that must be satisfied before the policy is issued, and the matters that will be excluded from coverage.

Although the exact format can vary by title company and transaction, most title commitments contain information about the proposed insured parties, the legal description of the property, the type and amount of title insurance coverage, and any conditions or exceptions that may affect the final policy.

Two of the most important parts of a title commitment are Schedule A and Schedule B, which are included in the standard commitment forms published by the American Land Title Association (ALTA). These sections help buyers, sellers, lenders, and their advisors understand the details of the proposed coverage and identify matters that may need attention before closing.

Schedule A of the Title Commitment

Schedule A generally contains the basic information about the proposed transaction and title insurance coverage. This may include the effective date of the commitment, the proposed insured party, the amount of insurance, the estate or interest being insured, and the legal description of the property.

For land buyers, the legal description deserves particular attention. Rural property is often identified by legal descriptions rather than a simple street address, so buyers should confirm that the description matches the land they intend to purchase. A land survey can also help clarify boundaries, acreage, easements, and other physical characteristics of the property.

Schedule B, Part I: Requirements

Schedule B, Part I typically lists the requirements that must be completed before the title company will issue the final title insurance policy.

These requirements may include paying off an existing mortgage, releasing a lien, providing documentation related to an estate or trust, correcting ownership information, or properly executing and recording transaction documents.

Some requirements are routine, while others may take additional time to resolve. Reviewing them early can help reduce the risk of unexpected delays before closing.

Schedule B, Part II: Exceptions

Schedule B, Part II identifies matters that the final title insurance policy may not cover. These are commonly referred to as title commitment exceptions or title insurance exceptions.

Depending on the property, exceptions may include easements, rights-of-way, restrictive covenants, recorded leases, mineral reservations, taxes or assessments, and certain survey-related matters.

For farm land and rural property, these exceptions can be especially important because they may affect access, utility placement, land use, or other rights associated with the property. Buyers should carefully review any exception they do not understand and seek guidance from the title company or a qualified real estate attorney when necessary.

How to Read a Title Commitment

Reading a title commitment can feel technical at first, but the document becomes easier to understand when you review it section by section. Buyers should focus on confirming the basic property information, understanding what must be completed before closing, and identifying any exceptions that could affect ownership or use of the land.

When reviewing a title commitment, pay close attention to the following:

  1. Confirm the property and ownership information
    Make sure the names of the parties, the type of ownership interest, and other basic transaction details are correct.
  2. Review the legal description
    The legal description identifies the property being insured. This is especially important for farm land, ranch land, and rural acreage where a street address alone may not fully describe the property.
  3. Read the title commitment requirements
    Review the items that must be completed before the title insurance policy can be issued. These may include paying off liens, providing documents, correcting ownership records, or completing other closing requirements.
  4. Examine the exceptions carefully
    Title commitment exceptions identify matters that may not be covered by the final policy. Easements, rights-of-way, mineral reservations, restrictions, and other recorded interests may appear here.
  5. Consider how recorded matters could affect the property
    An easement or restriction may be perfectly acceptable, but buyers should understand how it could affect access, farming operations, future improvements, utilities, or other intended uses of the land.
  6. Ask questions about anything that is unclear
    Buyers should not assume that every item listed in a title commitment is routine or unimportant. Questions about coverage can be directed to the title company, while legal questions may be better addressed by a qualified real estate attorney.

Carefully reviewing the title commitment before closing gives buyers an opportunity to identify concerns while there is still time to ask questions and determine whether additional action is needed.

Title Commitment vs. Title Insurance: What’s the Difference?

A title commitment and a title insurance policy are related, but they are not the same thing. The title commitment comes first and explains the conditions under which the title company is willing to provide coverage. The title insurance policy is issued after the transaction closes and provides the actual insurance coverage, subject to its terms, conditions, and exceptions.

A title commitment is essentially the title company’s conditional commitment to insure. It identifies the proposed insured parties, the property, the requirements that must be satisfied before closing, and the exceptions that may not be covered by the final policy.

By comparison, the final title insurance policy protects the insured party against certain covered title problems that existed before the policy was issued but were not otherwise excluded from coverage.

Title CommitmentTitle Insurance Policy
Issued before closingUsually issued after closing
Describes the proposed coverageProvides the actual coverage
Lists requirements that must be completedReflects the final insured terms
Lists exceptions that may not be coveredProvides protection subject to listed exceptions and exclusions
Helps identify issues before closingHelps protect against covered title defects after closing

For buyers, the title commitment is the document to review before the deal is completed. The title insurance policy is the protection that follows once the transaction closes and the insurer’s requirements have been satisfied.

What Should Land Buyers Look for in a Title Commitment?

For buyers of farm land, ranch land, recreational property, and other rural acreage, a title commitment can reveal recorded matters that may directly affect how the property is accessed, used, or transferred. Some items may be routine, while others deserve closer review before closing.

Land buyers should pay particular attention to:

  1. Access to the property
    Confirm whether the property has direct access to a public road or relies on an access easement across neighboring land. Legal access can be especially important for rural tracts that do not front a maintained roadway.
  2. Easements and rights-of-way
    Utility easements, pipeline easements, road easements, and rights-of-way may give other parties the right to use portions of the property. Buyers should understand where these areas are located and whether they could affect farming, grazing, improvements, or future development.
  3. Liens and other claims
    Existing mortgages, judgments, tax liens, or other recorded claims may need to be satisfied before the property can be transferred as expected.
  4. Mineral reservations and recorded interests
    Rural properties may be subject to previously recorded mineral reservations or other separate interests. Buyers should carefully review any related exceptions and seek qualified guidance when the ownership or extent of those rights is unclear.
  5. Restrictions and covenants
    Recorded restrictions may limit certain uses of the property, construction, subdivision, or other activities. These restrictions should be considered alongside the buyer’s intended use of the land.
  6. Legal description and boundary matters
    The legal description should accurately identify the property being purchased. If there are questions about boundaries, acreage, encroachments, or survey matters, buyers may need additional information before closing.

A title commitment does not necessarily mean that every listed easement, restriction, or exception creates a problem. The goal is to understand what affects the property and determine whether any recorded matter could interfere with the buyer’s plans for the land.

What Happens If a Title Commitment Shows a Problem?

Finding an issue in a title commitment does not automatically mean the transaction cannot move forward. Some title problems are routine and can be resolved before closing, while others may require additional review, documentation, or legal guidance.

Common issues that may appear during the title commitment process include:

  1. Outstanding liens
    Mortgages, tax liens, judgments, or other claims may need to be paid or released before the property can transfer as expected.
  2. Ownership discrepancies
    Public records may reveal questions about who currently holds title, particularly when property has passed through an estate, trust, divorce, or previous transfer.
  3. Errors in recorded documents
    Incorrect names, incomplete legal descriptions, missing signatures, or other recording issues may need to be corrected.
  4. Easements or restrictions
    A recorded easement, right-of-way, covenant, or restriction may affect access or how the property can be used.
  5. Boundary or survey concerns
    Differences between the legal description, survey, existing fences, or actual use of the property may require further investigation.

If an issue is discovered, the title company may identify what must be completed before it is willing to issue coverage. Depending on the situation, the seller, buyer, lender, title company, or other parties may need to provide documents, obtain releases, correct records, or resolve outstanding claims.

Some title defects can be handled relatively quickly, while more complicated matters may affect the timing or terms of the transaction. Buyers should review significant concerns with the title company and, when appropriate, a qualified real estate attorney before proceeding to closing.

When Is a Title Commitment Issued?

A title commitment is typically issued before closing, after the title company has completed its review of public records and other relevant documents associated with the property.

The exact timing can vary depending on the transaction, the property, the title company, and whether any issues are discovered during the title search. In many cases, the commitment is provided early enough for the buyer, seller, lender, and their advisors to review the requirements and exceptions before closing.

Receiving the title commitment early can be helpful because it gives the parties time to address outstanding liens, documentation issues, easements, ownership questions, or other matters that may need attention before the transaction is completed.

For land buyers, reviewing the commitment as soon as it is available can be especially important when the property involves access easements, rights-of-way, mineral reservations, unusual legal descriptions, or other recorded interests that could affect the intended use of the land.

Frequently Asked Questions About Title Commitments

Who Issues a Title Commitment?

A title commitment is generally issued by a title insurance company after it reviews public records and other information related to the property. The commitment explains the conditions under which the company is willing to issue a title insurance policy.

Is a Title Commitment the Same as Title Insurance?

No. A title commitment is issued before the final policy and outlines the proposed coverage, requirements, and exceptions. Title insurance is the actual policy that provides coverage after the transaction closes, subject to its terms and exclusions.

What Are Exceptions on a Title Commitment?

Exceptions are matters that may not be covered by the final title insurance policy. They can include easements, rights-of-way, restrictions, mineral reservations, recorded leases, taxes, and other matters affecting the property.

Does a Title Commitment Guarantee Clear Title?

Not necessarily. A title commitment identifies the conditions under which the title company is willing to provide coverage, but it does not guarantee that no title issues exist. Buyers should review the listed requirements and exceptions carefully.

Can a Title Commitment Delay Closing?

Yes. If the title commitment reveals liens, ownership issues, missing documents, recording problems, or other matters that must be resolved, closing may be delayed until those requirements are addressed.

Should Land Buyers Review a Title Commitment Before Closing?

Yes. Reviewing the title commitment before closing gives land buyers an opportunity to understand the legal description, requirements, exceptions, easements, liens, and other recorded matters that may affect the property.

Understanding a Title Commitment Before Buying Land

A title commitment is more than a formality in a real estate transaction. It gives buyers and sellers an opportunity to review important information about the property, understand the requirements that must be completed before closing, and identify exceptions that may affect the final title insurance policy.

For buyers of farm land, ranch land, recreational property, and other rural acreage, that review can be especially important. Easements, rights-of-way, liens, mineral reservations, legal descriptions, and other recorded matters may influence how the property can be accessed, used, or transferred.

Taking the time to understand the title commitment and asking questions about anything that is unclear can help buyers make more informed decisions before closing.

If you are considering buying or selling farm land, ranch land, or other rural property, the team at AgWest Land Brokers can help you navigate the real estate transaction and connect you with the appropriate professionals when title-related questions arise. So give us a call at 866-995-867 or reach out via our web form.
Understanding IRS Depreciation for Soil Fertility on Farmland

Farm Depreciation Rules - Soil Fertility Can Be Depreciated on Farmland

An Overview of Farm Depreciation Rules

Many landowners don’t realize that a portion of a farmland purchase may qualify for farmland depreciation under IRS guidance on farm depreciation—specifically related to soil fertility. Under established IRS rules and supporting case law, the cost allocated to wasting farm assets, such as residual fertilizer, lime, and soil nutrients present at the time of purchase, may be depreciated rather than permanently added to land value. See soil nutrient management and soil fertility.

While land itself is not depreciable, the IRS recognizes that certain soil fertility components are consumed over time through crop production. Because these nutrients decline with use, they may qualify for farm asset depreciation when properly documented and allocated during the purchase process.

In practice, IRS depreciation guidance allows specific components of a farmland acquisition to be treated as depreciable assets. Rather than assigning all value to non-depreciable land, certain soil nutrients can qualify for farmland depreciation and be included in a farm depreciation schedule.

How Soil Fertility Qualifies for Depreciation

To take advantage of these tax rules, buyers typically complete a soil fertility allocation study at or near the time of purchase. This study measures existing nutrient levels—such as nitrogen, phosphorus, potassium, and lime—and assigns a value to those nutrients based on current agricultural input costs. Learn about the importance of a farmland assessment checklist.

The purpose of this analysis is to identify nutrients already present in the soil that will be consumed through crop production over time. Because these nutrients gradually decline, they can qualify as a wasting asset eligible for farm asset depreciation rather than remaining permanently embedded in the non-depreciable value of the land.

Depreciation Schedule for Soil Nutrients

Once the fertility value has been determined, the allocated amount is depreciated over its useful life as part of a farm depreciation schedule. In many cases, soil fertility is depreciated over 4 to 7 years, depending on crop rotation, nutrient depletion rates, and management practices.

This structure allows producers and farmland investors to accelerate deductions compared with leaving the value permanently assigned to land. Properly documented farmland depreciation related to soil fertility can create significant front-loaded tax deductions and improve cash flow during the early years of ownership.

Why Soil Fertility Depreciation Matters for Farmland Investors

For producers and farmland investors—especially those acquiring irrigated or high-quality dryland acres—treating soil nutrients as depreciable assets can be a powerful but underutilized strategy.

When soil fertility is documented through professional testing and properly allocated at purchase, it may qualify for farm asset depreciation rather than remaining permanently embedded in land value. Coordinating this process with a CPA familiar with agricultural taxation ensures the depreciation treatment aligns with IRS guidance.

When implemented correctly, incorporating soil fertility into a farm depreciation schedule can materially reduce taxable income while preserving the long-term productive value of the land.

Ready to take the next step?

AgWest Land Brokers can help you understand the results of a farmland assessment before you make a decision to purchase. To see how we can help call 866-995-8067, send an email, or fill out our convenient web form.

Understanding Nebraska County Officials: Assessor, Clerk, and Treasurer

Image Not Found

Understanding how county government works is especially important for landowners, buyers, and taxpayers across Nebraska. Three key offices—the assessor, clerk, and treasurer—form the backbone of how property is valued, taxes are administered, and public records are maintained. While their roles are distinct, they are closely connected and work together to keep county operations running smoothly and transparently.

The County Assessor: Establishing Fair Property Values

The county assessor plays a critical role in the property tax system by determining the value of all real estate and taxable personal property within the county. This process is conducted annually and is guided by state laws to ensure consistency and fairness. The goal is simple in theory but complex in practice: establish equitable valuations so that each property owner pays their fair share of taxes—no more, no less.

To accomplish this, assessors analyze a wide range of data, including recent sales, market trends, soil productivity (particularly important for agricultural land), improvements to property, and depreciation. In rural areas, especially across central and western Nebraska, agricultural land values may be influenced by factors like irrigation availability, soil types, and commodity prices.

Beyond valuation, the assessor’s office is responsible for maintaining detailed property records. This includes parcel maps, ownership information, and legal descriptions of each property. These records are essential not only for taxation but also for real estate transactions, title work, and land management decisions.

The assessor also reviews and processes applications for property tax exemptions. Common examples include homestead exemptions for qualifying homeowners, as well as exemptions for religious, educational, or charitable organizations. Ensuring these exemptions are properly applied is another way the assessor helps maintain fairness in the tax system.

Additionally, the assessor serves on the County Board of Equalization, a governing body that hears protests from property owners who believe their valuations are inaccurate. This provides an important checks-and-balances system, allowing taxpayers to challenge assessments and ensuring compliance with Nebraska statutes.

The County Clerk: The Administrative Hub

If the assessor focuses on property values, the county clerk focuses on the processes and records that keep county government organized and accountable. Often described as the administrative hub of the county, the clerk’s office handles a wide variety of responsibilities that touch nearly every aspect of local government.

One of the clerk’s primary duties is serving as the official recordkeeper for the county board. This includes preparing meeting agendas, recording minutes, and maintaining resolutions and official actions taken by county commissioners. These records ensure transparency and provide a historical account of decisions that impact the community.

The clerk is also responsible for maintaining a wide array of official county documents. This can include contracts, financial records, oaths of office, and other legal filings. Accuracy and organization are essential, as these records are often referenced for audits, legal matters, and public inquiries.

In many Nebraska counties, the clerk plays a central role in elections. This includes overseeing voter registration, coordinating polling locations, and ensuring compliance with state and federal election laws. In counties without a separate election commissioner, the clerk essentially serves as the chief election official.

Administrative functions are another major component of the clerk’s role. From processing payroll for county employees to managing record retention policies and submitting required reports to the Nebraska Secretary of State, the clerk ensures that the day-to-day operations of county government remain efficient and compliant.

The County Treasurer: Managing Revenue and Collections

While the assessor determines property values and the clerk maintains records, the county treasurer is responsible for collecting and managing the money that funds local services. As the county’s chief financial custodian, the treasurer’s office handles the billing and collection of property taxes, which are a primary source of revenue for schools, roads, emergency services, and other public needs.

Each year, tax statements are generated based on the valuations set by the assessor and the levies established by local taxing entities. The treasurer collects these payments and ensures they are distributed accurately to the appropriate jurisdictions, such as school districts, municipalities, and natural resource districts.

In addition to property taxes, the treasurer’s office often manages motor vehicle services. This includes issuing titles and registrations for cars, trucks, and boats. In many counties, the office also provides driver’s license and state ID services, making it a frequent point of contact for residents.

Financial management is another key responsibility. The treasurer oversees county bank accounts, reconciles daily transactions, and ensures that all funds are properly accounted for. This requires a high level of accuracy and accountability, as even small discrepancies can have significant impacts.

Working Together: A System That Supports Landowners

Although each office has its own responsibilities, the assessor, clerk, and treasurer are deeply interconnected. The assessor establishes property values, the clerk documents and supports the administrative framework, and the treasurer collects and distributes the resulting tax revenue. Together, they form a system that ensures fairness, transparency, and efficiency.

For landowners and agricultural producers, understanding these roles can be especially valuable. Whether you are reviewing your property valuation, filing an exemption, paying taxes, or researching records, these offices are the primary points of contact. Their work directly impacts land values, operating costs, and long-term investment decisions.

In a state where agriculture and land ownership are central to the economy, these county officials play a vital role in maintaining trust in the system. By ensuring accurate records, fair valuations, and responsible financial management, they help support not only local government operations but also the broader stability of Nebraska’s land market and rural communities.

Contact us with questions

To see how we can help call 866-995-8067, send an email, or fill out our convenient web form.

Benefits of Title Insurance

Image Not Found

When buying or selling land in Nebraska, title insurance is one of the most important safeguards you can have in place, even though it isn’t legally required for every transaction. A thorough title search can uncover many issues, but it cannot guarantee that every potential defect or claim will be found in public records. Title insurance protects you from financial loss if a hidden problem — such as a forged deed, undisclosed heir, unpaid lien, or recording error — arises after closing and challenges your ownership rights. Without this protection, resolving a title dispute could cost you tens of thousands of dollars in legal fees or force you to defend your property rights in court.

In Nebraska, title insurance also offers peace of mind and marketability that can make buying or selling land smoother. Lenders typically require a lender’s title insurance policy to protect their investment, and adding an owner’s policy ensures your financial interest in the property is covered as well. An owner’s policy lasts for as long as you or your heirs own the land, guarding against claims from past events that weren’t discovered before closing. This protection not only reduces risk for you today but also makes the property more attractive to future buyers by demonstrating clear, insured ownership.

Nebraska Documentary Taxes

Image Not Found

When you close on a land sale in Nebraska, one of the taxes you’ll encounter is the documentary stamp tax, a state transfer tax imposed on the transfer of real estate. This tax is required when the deed is presented for recording with the county Register of Deeds, and it’s based on the value of the property being transferred — typically the full purchase price or market value if the sale involves nominal consideration. The documentary stamp tax is calculated at about $2.32 for every $1,000 of property value (or fraction thereof), with the amount affixed as a “stamp” on the deed to show that the tax has been paid before recording. This tax is generally paid by the seller as part of closing costs unless otherwise negotiated in the purchase agreement.

The purpose of documentary stamps is to generate revenue for state and county funds and to ensure that real estate transfers are properly documented in public records. Many deeds are presumed taxable under Nebraska law unless a specific statutory exemption applies — such as transfers between spouses, certain family transactions, or transfers into some trusts — and the deed or accompanying paperwork must clearly indicate if an exemption is claimed. Because documentary stamps are a state requirement tied to transferring title, the title company or closing agent will typically calculate this amount, collect it at closing, and ensure the deed is stamped and recorded correctly so that the buyer takes clear, marketable title.

Title Company Duties

Image Not Found

When you buy or sell land, a title company plays a central role in making sure the transaction closes smoothly and legally. Long before closing day, the title company conducts a comprehensive title search by examining public records to confirm that the seller truly owns the property and that there are no liens, unpaid taxes, easements, or other issues that could cloud ownership. If any problems are found — such as an undisclosed lien or ownership discrepancy — the title company works to resolve them before the sale can proceed, protecting buyers from inheriting legal or financial headaches. Once the search is complete and any concerns are addressed, the company issues title insurance to the buyer and lender, providing financial protection against future claims that weren’t uncovered during the search.

During the actual closing, the title company acts as a neutral facilitator and escrow agent, preparing and organizing all required documents, coordinating signatures, and managing the flow of funds. They prepare the deed, settlement statements, and any affidavits, and they hold escrow funds such as the buyer’s payment and lender proceeds until all terms of the purchase agreement are satisfied. On closing day, their representative guides both parties through the documents, ensures everything is properly signed and notarized, and disburses funds — including paying off existing liens, commissions, and property taxes — before handing proceeds to the seller. After the closing, the title company records the deed and other legal documents with the county, officially transferring ownership and then issues the finalized title insurance policies.

Why Getting a Survey Done is a Good Idea

Image Not Found

When buying or selling land — especially agricultural acreage, pasture, or rural property — a land survey provides clarity and peace of mind by showing the exact boundaries, acreage, and features of the parcel you are transacting. Surveys are performed by licensed professionals who physically measure and map the property, rather than relying on possibly outdated or imprecise records. This ensures both buyers and sellers know exactly what is being exchanged, which is critical for pricing, financing, and future use. A survey will also alert you to easements, rights‑of‑way, or encroachments that could affect where you can build, fence, or farm, helping prevent disputes with neighbors later on.

For sellers, providing a recent survey can increase buyer confidence, speed up the transaction, and reduce negotiations around boundary questions, as it demonstrates transparency and preparedness. Many lenders and title companies also require or strongly prefer a current survey to approve mortgages and issue title insurance, adding another layer of protection for everyone involved. While surveys add upfront cost and take time to complete, they help avoid costly legal disputes, boundary disagreements, or development issues down the road, making them a smart step in any land sale or purchase.

Benefits of Hiring a Full-Time Land Broker

Image Not Found

When selling farmland or acreage, choosing a full‑time land broker over a part‑time agent can make a significant difference in your experience and the final sale outcome. Full‑time brokers devote all of their professional hours to real estate — which means they’re more available to respond quickly to inquiries, show your property at convenient times, and stay on top of every detail throughout the transaction. In contrast, part‑time agents often juggle another job or responsibilities, which can limit their responsiveness and flexibility when buyers or questions arise — potentially slowing down the sale process or missing opportunities to engage serious buyers.

A full‑time land broker also brings deeper market expertise and a larger network developed from constant involvement in land transactions. Because they live and breathe the land market — tracking trends, connecting with active buyers and investors, and participating in ongoing education — they tend to have a better understanding of pricing nuances, effective marketing strategies, and negotiation tactics that can help you sell your property at a stronger price and with fewer hassles. Their broader contact base and professional marketing capabilities (including MLS access, targeted advertising, and extensive local networks) increase exposure to qualified buyers far more than casual part‑time efforts typically do.

Ultimately, selling land — especially specialized property like farmland, pasture, or recreational acreage — is a unique process that benefits from focused expertise, timely communication, and proactive service. A full‑time land broker brings these advantages to the table, helping reduce stress, minimize delays, and often achieve better results for sellers who want to maximize value and close with confidence.

Benefits and Downfalls of Grazing Corn Stalks

Image Not Found

Grazing corn residue — leaves, husks, and stalks left after harvest — can be a useful tool for Nebraska producers when managed correctly. Long‑term research at the University of Nebraska shows that grazing corn stalks in the fall or winter does not lead to significant soil compaction or measurable declines in soil structure, organic matter, or nutrients, and often leaves enough residue cover (generally less than 20% removal) to protect against erosion and maintain soil health. In some studies, grazed fields even showed no negative impact on subsequent crop yields and slight increases in soil microbial activity that can enhance nutrient cycling. Grazing can also serve as a residue management strategy, helping break down excess plant material while cattle return much of the nutrients they consume back to the field through manure and urine.

However, there are potential downfalls that landowners and tenants should consider. Removing too much residue — especially on fields with low initial stalk volume or steep slopes — can reduce ground cover and potentially increase wind or water erosion risk if not managed carefully. Grazing on wet or thawing soils can create surface roughness or localized compaction that might temporarily affect seed placement or early spring operations, and even though overall compaction effects are generally minimal, timing and stocking density matter. Planning grazing rotation, monitoring residue levels, and coordinating stocking rates helps ensure that soil protection goals are met while still capturing the benefits of stalk grazing.

Absolute Auction vs. Private Treaty Listing

Image Not Found

When selling farmland, one major decision a landowner faces is whether to use an absolute auction or a private treaty listing. An absolute auction — sometimes called a no‑reserve auction — means the land will be sold to the highest bidder regardless of price once bidding closes at the set date and time. Because there’s no minimum or reserve price, absolute auctions can generate strong competitive bidding and a quick sale date, with contracts typically finalized immediately when the hammer falls. This method is transparent and can attract multiple buyers who know the property must sell on auction day, which can help establish fair market value in real time.

In contrast, a private treaty listing is the traditional way to sell land, where the seller and agent set an asking price and then negotiate offers privately with interested buyers over time. There’s no fixed end date, and both price and terms — like closing dates or contingencies — can be negotiated until both parties agree. Private treaty sales offer more flexibility and control for the seller and more time for buyers to arrange financing or due diligence, but they can take longer to complete and don’t create the same competitive urgency that an auction does.